
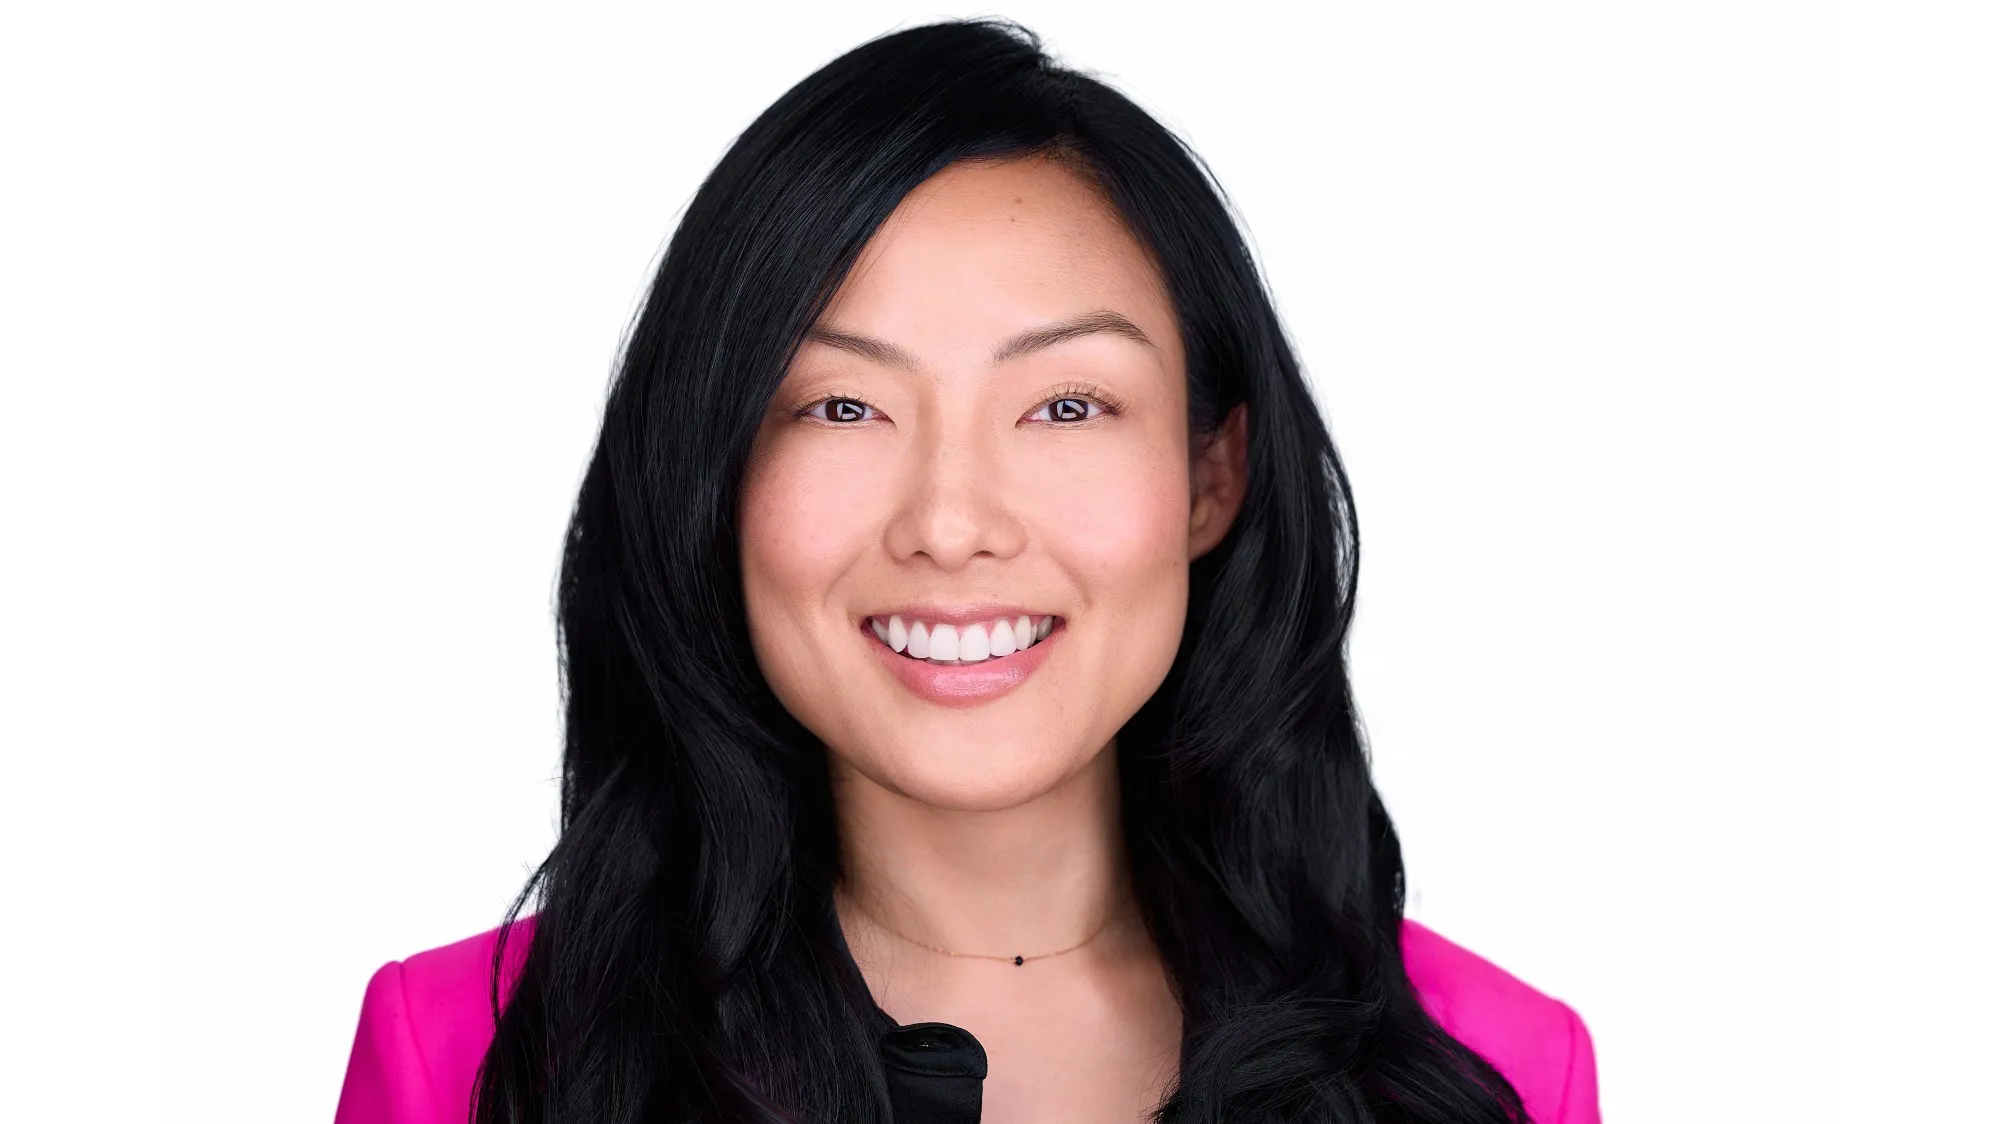
Ahead of the November general election, the Southern California News Group compiled a list of questions to pose to the candidates who wish to represent you. You can find the full questionnaire below.
Read more 21 free fun things to do for Halloween 2026 in Southern California
Name: Jane Kim
Age: 49
Current job title: Former California Director of Working Families Party
Political party affiliation: Democrat
Incumbent: No
Other political positions held: Elected offices currently held: San Francisco Democratic County Central Committee Elected offices previously held: San Francisco Board of Education (2006-2010), San Francisco Board of Supervisors (2011-2019)
City where you reside: San Francisco
Campaign website or social media: www.janekim.org
The litigation from across the country is piling up on State Farm. Since the L.A. wildfires, the Illinois insurance giant has claimed that it could become insolvent — which is why it sought double-digit rate increases from homeowners over the past two years. Commissioner Ricardo Lara has found that State Farm must pay millions in fines for failing to pay claims filed after the fires for one reason or the other, and this summer, Oklahoma’s attorney general alleged that State Farm “engaged in a coordinated scheme to wrongfully deny or underpay legitimate hail and wind damage claims” submitted by homeowners there. Some observers say State Farm stands a chance of pulling back in California, or even reorganizing the company under bankruptcy laws because of its financial problems. What can you do to help State Farm stay? (Please answer in 200 words or less.)
Californians are seeing through the same old pattern from corporations like State Farm. They charge us more and more for a product that is only getting worse. And throughout the process, companies threaten to leave the state in order to demand higher rates. California is the nation’s largest insurance market. State Farm doesn’t want to leave the state – what they want is the ability to drive up profit margins. This game hurts consumers and does nothing to make our system more stable in the long term.
The way to keep companies like State Farm here long-term is to create a stable, transparent system where we incentivize and invest in risk reduction, and rate decisions are based on data instead of threats. I’m proposing an approach to insurance that actually ties the price of insurance to savings from climate risk mitigation, and creates an incentive to maximize stability instead of maximizing profits. Threats to leave should not be carte blanche for corporations like State Farm to rip Californians off.
Does the FAIR Plan need a legislative fix? How will you reduce wildfire risks and depopulate the insurer of last resort — called the Fair Access to Insurance Requirements Plan? (Please answer in 200 words or less.)
The FAIR plan is expensive and must be dramatically reformed. Run by the insurance industry, it’s become a dumping ground for the riskier customers that they don’t want to underwrite themselves. When the FAIR plan has a profit surplus, it gets redistributed back to the insurance companies. When the FAIR plan loses money, insurance companies pass on the cost to every policyholder in the state through assessments. They’re privatizing profit and socializing costs.
I will propose making the FAIR Plan financials and governing board public. Right now, the FAIR Plan Governing Board does not disclose when they meet, and we know very little about how the plan is structured or managed. I’d require surplus profits to be reinvested in making homes and communities safer.
Ultimately, the FAIR Plan should be shrinking, not growing. But this will only happen if communities are safer and insurers compete to write that business again.
Jane Kim wants to reduce risk through a “universal disaster insurance for all” plan that would make coverage automatic and universal, with everyone in the same risk pool and premiums based on property cost and risk. Why is this good or bad for individual policyholders? (Please answer in 200 words or less.)
The current insurance system is a failure, and we cannot keep tinkering with it while hoping to achieve different results. Right now, the market is not designed to handle increasing wildfire risk. Instead of investing in efforts that make homes and communities safer – and eventually bring costs down for everyone, homeowners and insurers alike – insurance companies simply demand broad price increases or drop coverage when things get riskier in the state. And it’s been a winning strategy for them: insurance companies are making more and more money as we get less and less coverage.
A Disaster Insurance for All program would be an efficient solution to cover losses from natural disasters and accomplish two things. First, this program would prioritize and fund climate risk mitigation on a community-wide basis. Second, it would use savings from our premiums to fund more risk reduction, because a public, nonprofit program would be accountable to working people, not shareholders and CEOs. The program would also only cover existing homes so people are not incentivized to build new homes in high-risk areas.
This solution maximizes safety over profits, and it’s an idea big enough to actually address the scale of our insurance crisis.
Ben Allen says the state needs to encourage policies to reduce risk at its source by investing in wildfire mitigation and making communities more fire-safe — a policy that will eventually depopulate the FAIR Plan. Why is this good or bad for individual policyholders? (Please answer in 200 words or less.)
We agree that wildfire risk has to decrease. But Ben Allen has not proposed a plan to do this at the scale our state needs, perhaps because he’s afraid to stand up to the utility and insurance industries.
Many Californians have already hardened roofs, cleared brush, and retrofitted their homes. But the benefits have largely flowed to insurers as avoided claims, not back to homeowners as lower premiums or higher discounts. And, most importantly, individual families cannot, on their own, make their community safe – that has to be a collective effort incentivized and managed by the state. If the plan is to keep asking individual families to fund mitigation, we’ll keep seeing rates skyrocket while more homeowners – even ones who made their individual homes safer – get dropped.
That’s why I’m proposing a solution that will actually make us safer and bring costs down. A public nonprofit program would use our premium dollars to mitigate risk at the scale we need, rather than using premiums to fund shareholder payouts, private jets, and CEO bonuses. This will bring down our risk in the long term and will do it in a way that’s fair to Californians.
Where do you stand on AB 1795, the Smoke Damage Recovery Act? The proposal was unveiled earlier this year by the current insurance commissioner and Assemblymember Mike Gipson. The bill would establish California’s first enforceable public health and insurance claims standards for smoke-damaged homes. Does this legislation go far enough to appease victims from the L.A. wildfires who say that insurers haven’t been fair in claims payouts on smoke damage? (Please answer in 200 words or less.)
AB 1795 is a step in the right direction toward a clearer standard for smoke damage and making insurers accountable for testing to make sure a home is safe from toxins. But there’s still significant work that needs to be done to make sure the standards continue to prioritize safety instead of convenience and profit for insurance companies. Survivors shouldn’t have to wait this long to get an honest answer about whether their home is safe to come back to, and whether or not they can expect a fair payout for smoke damage. I’ll do everything in my power to get that answer to them faster so that people can move forward with rebuilding their lives.
Do you support Vermont Sen. Bernie Sanders’ views on insurance, to replace the current multi-payer private home insurance market and the FAIR Plan with a centralized, state-managed system to cover wildfire and flood risks? Why, or why not, is this a good approach? (Please answer in 200 words or less.)
I’m proud that U.S. Sen. Bernie Sanders has endorsed my campaign for insurance commissioner. Bernie understands the importance of bringing costs down for working people, and I’m honored to stand alongside him in the fight for insurance for all. He popularized Medicare for All, which follows the same principle of Disaster Insurance for All: safety and security should be a right, not a privilege.
A public, nonprofit Disaster Insurance for All system works because it reinvests our premium dollars back into making our entire state safer and more prepared for increased wildfire risk. Insurance companies won’t do this because that would cut into their massive profits, which currently go to shareholders’ dividends and CEO bonuses.
Read more Russia reports a worker at a Siberian plague institute got pneumonia from an unknown cause and died
Californians are required to have insurance to participate in the economy: to buy a car, a home, or open a business. But we’re being ripped off by insurance companies who don’t actually care about making us safer, especially when it gets in the way of driving up their massive profit margins. Bernie and I agree that enough is enough. Californians work hard for their money, and we deserve an insurance system that makes us safer and provides value to its customers.
Should insurance executive pay be capped? Why or why not? (Please answer in 200 words or less.)
Yes, insurance executive pay should be capped. Insurance is mandatory for all Californians who want to participate in our economy. No executive should be able to take advantage of that and get paid excessively for continuing to raise rates and drop policies. Instead of awarding executives for growth and profitability only, which often comes at the cost of affordability of insurance for working families, we need a system that awards true risk mitigation. Executives should have a stake in making insurance affordable and available for the very Californians whose premiums pay for the millions in bonuses and private jets.
Does the FAIR Plan need more transparency – like having the governing board be restructured to include consumer advocates, homeowners, labor and elected officials and independent financial experts? Why or why not? (Please answer in 200 words or less.)
The FAIR Plan absolutely needs more transparency. The FAIR Plan is entirely controlled by the insurance industry, and the public has no view of who sits on the governing board or any of its financials. It’s used as a dumping ground for home and business owners that insurance companies don’t want to cover. These customers pay sky-high premiums because they have no other choice. No one I’ve ever spoken to on the FAIR Plan is happy with it.
The FAIR Plan also passes on assessment costs, which are fees charged when the FAIR Plan runs out of money, to all Californians when disasters hit and returns any profit surplus it makes to the insurance companies. It does nothing to help make homes and communities safer in the long term. Since the beginning of the campaign, I have stated that consumer advocates, labor and elected officials should sit on the governing board, so that it can be directed to protect consumers instead of only protecting the bottom line of the insurance industry. We also need full transparency on how the FAIR plan makes its decisions and its financials so we, as the public, can audit for fairness.
What do you think about the consequences for insurers threatening to leave the state? Should they pay an exit fee? Should insurers be able to cherry-pick which lines of business they keep? (Please answer in 200 words or less.)
Right now, insurance companies are having their cake and eating it, too. They cherry-pick the lower-risk, lower-cost customers and drop everyone else. Then, even though they’ve already dropped the higher-risk homes, they use the growing level of risk in California to charge more to their remaining, lower-risk customers. It’s a PR strategy: They use the fear-mongering headlines about leaving the state to justify rate increases on homes that are lower-risk. We haven’t seen any insurance companies truly exit the state entirely, because California is the largest insurance market in the country, with 40 million people who pay into insurance to create a strong, resilient, and powerful economy. No one wants to totally leave behind the opportunity to participate in the California market. We need to start acting like the economic powerhouse that we are and set the terms for what a stable market should look like and how insurance companies should play so they can make enough money without ripping off its customers or holding the state hostage.
I’m open to exploring an exit fee, but I’m more interested in policy solutions that expand coverage availability and affordability from insurers rather than penalize an exit.
Should insurers be required to regularly report key metrics including the number of claims filed, claims denied or closed without payment, and processing timelines? Why or why not? (Please answer in 200 words or less.)
Yes. Markets work better when buyers have information, and right now customers can only compare prices when they shop for a new plan. They should be able to access information about how well an insurance company treats its customers and honors its contractual obligations. This includes claims denial rates, how many claims get closed without payment, and how long processing actually takes. Those are the data that tell you what you’re really buying, and none of that is easily accessible today for an everyday consumer who is looking into what coverage to buy. Requiring insurers to report this data regularly creates real competitive pressure on claims handling itself, not just on price, since companies with bad claims records would have to compete for customers who can see that record. It would incentivize insurers to compete on quality, not just price.
Given Commissioner Ricardo Lara’s disdain for Consumer Watchdog, an advocacy group that fights to lower insurance costs, how can the relationship be improved? Critics, like Lara, say that Consumer Watchdog is more interested in profiting as an “intervenor” in rate cases where private insurers are trying to raise premiums. What would you do to improve the relationship — or is it not repairable? (Please answer in 200 words or less.)
I’ll work with any group that fights for consumer rights, and I’ll hold them to the same transparency standard I’d hold the department or the industry to. The intervenor process exists because insurance policyholders have traditionally had very little power to hold the industry accountable to setting fair prices against large, well-funded legal teams employed by insurance corporations. My priority is making sure the department itself is resourced and focused enough to be the first line of defense against unfair or excessive price increases. Intervenors should be allies that help support the goals of the Department of Insurance in protecting consumers. They shouldn’t be a substitute for a department that isn’t doing its job.
Tell us what in your background has best prepared you for this role. (Please answer in 200 words or less.)
The insurance commissioner job comes down to three things: negotiation, regulation, and legislation. As an attorney and supervisor, I bring extensive experience across all three dimensions.
But Californians need an insurance commissioner who has a history of delivering real wins that materially improve their lives. As a San Francisco supervisor for two terms, I represented a district encompassing both the city’s lowest-income residents and its wealthiest ZIP code. I fought for landmark initiatives, including making San Francisco the only city in the nation to provide tuition-free community college for all residents and enacting the nation’s strongest minimum wage law. I also led the single largest investment any U.S. city has made toward early childhood education, passing a tax on multimillion-dollar commercial real estate that now raises over $140 million annually to make universal affordable childcare a reality.
On top of that, I am the only candidate who has spent a decade organizing and working with communities across the entire state of California. My relationships from Imperial County to Siskiyou have provided me with a unique perspective on the complex communities that make up California, from rural to urban, and the unique challenges they face right now.
Tell us about a time you’ve changed your mind on a political position. What was it, and what changed your mind? (Please answer in 200 words or less.)
I was in office during a housing boom, and I negotiated with market-rate developers to win record levels of affordable and middle-income housing, winning more affordable units than any California legislator — while never denying a project. Over my two terms, I negotiated and passed 80% of San Francisco’s residential and commercial development in my district. However, this strategy relies on a strong market. While I’m proud of my record, ultimately growing federal and state resources to build affordable housing is the best way to scale construction to combat the affordability crisis
Bonus question: What is the best book you’ve read this year? Explain why you found it compelling.
“Things Become Other Things” by Craig Mod – a heart-achingly beautiful memoir centered around the author’s reflections growing up in a factory town, sparked by his solo walk retracing the Kumano Kodō, the ancient pilgrimage path through Japan’s southern Kii Peninsula. It is a poignant reflection on towns and memories left behind, written in beautifully reflective prose.
Read more A new Supreme Court term begins with cases on climate change, immigration and gun rights